Uncategorized

11.9.26

Credit: iStock.com/skynesher

The health care industry is experiencing profound changes driven by rising medical costs, artificial intelligence (AI), breakthrough pharmaceuticals, an aging population and advances in biotechnology. Hospitals, insurers, pharmaceutical manufacturers and health care providers are investing heavily in technology while struggling to control expenses and improve patient outcomes. At the same time, innovative business models are transforming how medical services are delivered, creating significant opportunities for companies throughout the industry.

Even more information on this industry is available!  Check out our Health Care Industry Center.

Plunkett’s Health Care Industry eBook, latest edition.

1. Health Care Spending Continues to Soar

      Rising health care expenditures remain one of the industry’s greatest challenges. According to the Centers for Medicare and Medicaid Services (CMS), U.S. health care spending was projected to reach $5.66 trillion in 2025, compared to $5.26 trillion in 2024. Health care represents approximately 18% of U.S. gross domestic product, making it one of America’s largest economic sectors.

      Hospital services, physician care and prescription drugs account for much of this spending. Increasing labor costs, expensive medical technologies, hospital consolidation and rising pharmaceutical prices are placing substantial financial pressure on patients, employers and insurers.

      Employers are responding by increasing employee contributions toward premiums, deductibles and copayments. Many are also investing in wellness programs, preventive care and workplace clinics to reduce long-term medical expenditures.

      2. Artificial Intelligence Revolutionizes Medical Services

      AI is rapidly becoming one of the most transformative technologies in health care. Hospitals and physician groups are implementing AI systems to improve diagnostics, automate administrative tasks, analyze medical images and monitor patients.

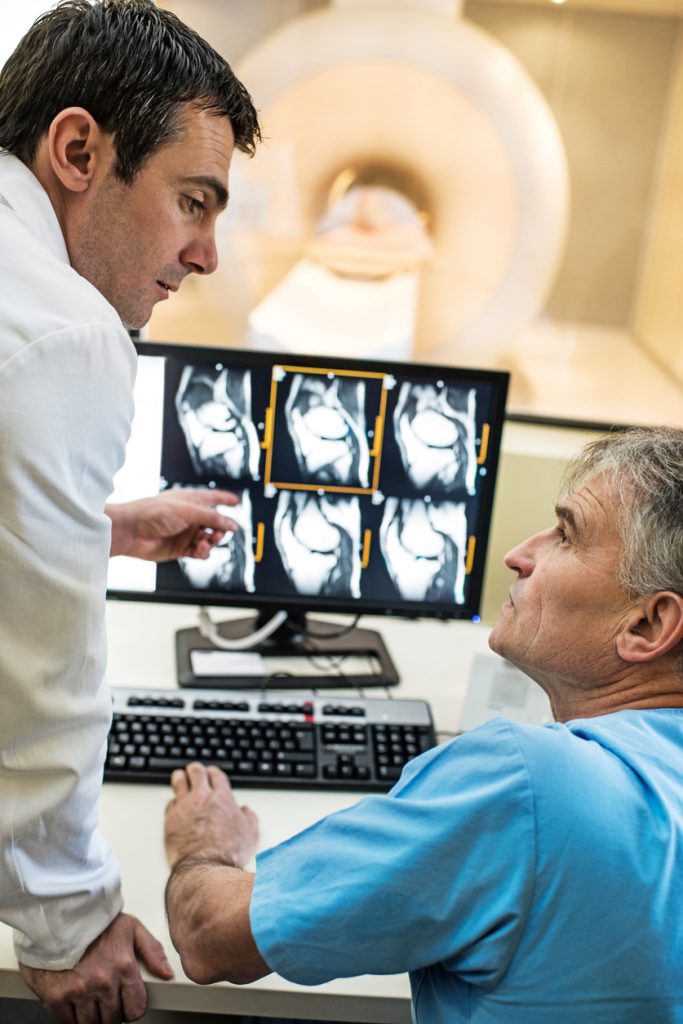
      AI-powered software can identify abnormalities in X-rays, MRIs and CT scans, potentially enabling earlier detection of cancer and other diseases. Generative AI tools are also automating clinical documentation, allowing physicians to spend less time preparing medical records and more time treating patients.

      Meanwhile, pharmaceutical companies are applying machine learning to drug discovery, identifying promising compounds and potentially shortening development timelines.

      Investment in health care AI continues to accelerate. Companies developing AI-based clinical documentation, administrative automation and diagnostic technologies are attracting substantial venture capital funding.

      However, questions surrounding patient privacy, algorithmic accuracy, regulatory oversight and liability remain important challenges.

      3. GLP-1 Drugs Transform Obesity Treatment

      The emergence of GLP-1 medications represents one of the most significant pharmaceutical breakthroughs in recent years. Drugs including Novo Nordisk’s Ozempic and Wegovy and Eli Lilly’s Mounjaro and Zepbound have demonstrated remarkable effectiveness in treating diabetes and obesity.

      Clinical studies have shown that certain patients taking these medications can lose approximately 15% to 21% of their body weight, depending on the drug and treatment regimen.

      Their potential extends far beyond weight management. Research indicates that GLP-1 medications may help reduce cardiovascular risks, improve kidney health and treat sleep apnea. Scientists are also investigating potential applications involving addiction and other medical conditions.

      The development of oral weight-loss medications, additional competing products and lower-cost alternatives could dramatically expand the market. As pharmaceutical manufacturers pursue new treatments, GLP-1 drugs may become among the most commercially important medication categories in history.

      4. Aging Baby Boomers Drive Medicare and Long-Term Care Spending

      America’s aging population is creating unprecedented demand for medical services. Medicare provided coverage to approximately 69.3 million Americans in 2025, with enrollment projected to exceed 80 million by 2034.

      As Baby Boomers grow older, demand is increasing for hospitals, nursing facilities, home health services, prescription medications and chronic disease management.

      Older Americans frequently require treatment for multiple chronic conditions, including diabetes, cardiovascular disease, arthritis and dementia. Consequently, Medicare and Medicaid expenditures are placing growing pressure on federal and state budgets.

      The aging population is also creating opportunities for companies specializing in assisted living, home-based care, medical devices and remote patient monitoring.

      5. Hospitals Consolidate While Value-Based Care Expands

      Hospital mergers and acquisitions have transformed the competitive landscape. Large health systems increasingly control substantial regional market shares, while independent physician practices face pressure to join larger organizations.

      Consolidation can provide economies of scale, improved technology investments and greater administrative efficiency. However, reduced competition may also contribute to higher medical prices.

      Meanwhile, insurers and government programs are encouraging value-based care, which rewards providers for patient outcomes rather than the volume of services performed.

      Accountable Care Organizations (ACOs) and other alternative payment arrangements emphasize preventive medicine, coordinated treatment and reduced hospital readmissions.

      These approaches could improve quality while helping restrain long-term expenditures.

      6. Telemedicine and Alternative Health Care Models Expand

      Health care delivery is increasingly moving beyond traditional hospitals and physician offices. Telemedicine, remote patient monitoring, urgent care facilities and outpatient surgical centers are providing more convenient alternatives.

      Patients can consult physicians through video appointments, while wearable devices and connected medical equipment allow providers to monitor blood pressure, glucose levels and cardiovascular conditions remotely.

      Companies such as Amazon, through One Medical, are expanding their presence in primary care and virtual medical services.

      Concierge medicine and direct primary care are also gaining attention. These models typically charge patients membership fees in exchange for more personalized services and improved access to physicians.

      For many patients, these alternatives offer greater convenience, although affordability and insurance coverage remain important considerations.

      7. Biotechnology and Personalized Medicine Advance

      Rapid progress in genetic sequencing, immunotherapy and precision medicine is creating new approaches to treating serious diseases.

      Cancer treatment is undergoing particularly significant innovation. CAR-T cell therapies modify patients’ immune cells to attack certain cancers, while antibody-drug conjugates deliver powerful medications directly to targeted cancer cells.

      Other emerging technologies, including protein degraders and advanced gene therapies, offer promising approaches to diseases that historically have been difficult to treat.

      Meanwhile, declining DNA sequencing costs are making personalized medicine more practical. Physicians increasingly can use genetic information to identify disease risks and select treatments suited to individual patients.

      Stem cell research, regenerative medicine and 3D printing are also creating opportunities for tissue repair and potentially more sophisticated medical treatments.

      8. Robotics, Advanced Imaging and Digital Records Improve Efficiency

      Health care providers are investing in robotic surgery, advanced diagnostic imaging and electronic health records.

      Robotic-assisted surgical systems can improve precision and enable minimally invasive procedures, potentially reducing recovery times and hospital stays.

      Advanced MRI, PET and CT imaging technologies are improving the detection and monitoring of disease.

      Electronic health records enable providers to share patient information more efficiently, while integrated digital systems support improved coordination among hospitals, specialists and insurers.

      These technologies require substantial capital investments but offer opportunities to improve productivity and patient care.

      9. Health Care Workforce Shortages Create Challenges

      Hospitals, nursing facilities and other providers continue to face difficulties recruiting and retaining qualified workers.

      Demand for nurses, physicians, technicians and home health aides is increasing as the population ages. Staffing shortages can raise labor expenses, limit available services and contribute to employee burnout.

      Health systems are responding through workforce training, automation, improved scheduling and expanded use of technology.

      AI-assisted documentation and remote monitoring may help reduce administrative burdens, although technology cannot replace many essential hands-on medical services.

      10. The Future

        The health care industry offers enormous opportunities for technological innovation and business expansion. Artificial intelligence, biotechnology, GLP-1 medications, robotic surgery and personalized medicine are reshaping the diagnosis and treatment of disease.

        At the same time, aging populations, rising insurance premiums, expensive pharmaceuticals and workforce shortages will continue to challenge providers, patients and policymakers.

        The industry’s greatest opportunity lies in combining medical breakthroughs with more efficient delivery systems. Companies that successfully improve patient outcomes, expand access to care and control costs will be well positioned to succeed in the rapidly evolving global health care market.

        Key Concepts:  Biotechnology, business, healthcare, economics, healthcare, entrepreneurship, finance, hospitals, globalization, drugs, innovation, investing, marketing, pharmaceuticals, technology, robotics, artificial intelligence (AI), predictive analytics

        Source: Plunkett Research, Ltd., Copyright © 2026
        Plunkett Research, Ltd., a Houston, Texas-based market research firm, has completed its latest research on the Health Care Industry.  (See: https://www.plunkettresearch.com/industries/health-care-medical-market-research/).  This revised and updated data is part of our massive Plunkett Research Online subscription service, where we continuously monitor the world’s 40 most vital business sectors, including such industries as retailing, artificial intelligence, health care, sports/recreation and much, much more.  Our analysts and market research continually monitor the world’s leading industries and companies and post thorough updates yearly.

        Key Findings:

        A complete market research report, including forecasts and market estimates, technologies analysis and developments at innovative firms within the Health Care Industry.  Gain vital insights that can help shape strategy for business development, product development and investments.

        Key Features:

        • Business trends analysis
        • In-depth industry overview
        • Technology trends analysis
        • Forecasts
        • Spending, investment, and consumption discussions
        • In-depth industry statistics and metrics
        • Industry employment numbers

        Additional Key Features Include:

        Industry Glossary

        Industry Contacts list, including Professional Societies and Industry Associations

        Profiles of industry-leading companies

        • U.S. and Global Firms
        • Publicly held, Private and Subsidiaries
        • Executive Contacts
        • Revenues
        • For Public Companies: Detailed Financial Summaries
        • Statistical Tables

        Key Questions Answered Include:

        • How is the industry evolving?
        • How is the industry being shaped by new technologies?
        • How is demand growing in emerging markets and mature economies?
        • What is the size of the market now and in the future?
        • What are the financial results of the leading companies?
        • What are the names and titles of top executives?
        • What are the top companies and what are their revenues?

        This feature-rich report covers competitive intelligence, market research and business analysis—everything you need to know about the Health Care Industry.

        Plunkett Research Provides Unique Analysis of the Following Major Trends and Technologies Affecting the Health Care Industry

        1. Major Trends Affecting the Health Care Industry
        2. Introduction to the Health Care Industry
        3. Continued Rise in Health Care Costs
        4. Employers Fight Rapidly Growing Health Care Premiums/Require Employees to Pay a Significant Share of Costs
        5. Medicare and Medicaid Spending Continue to Surge/More Baby Boomers Hit 65+ Years of Age
        6. U.S. Affordable Care Act (ACA) of 2010 Rewrote the Rules and Increased Coverage, But Costs Continue to Rise
        7. Accountable Care Organizations (ACOs) and Hospital Mergers Result from the Affordable Care Act/Many Hospital Chains Grow Dramatically in Market Share
        8. Concierge Care/Direct Primary Care Are on the Rise/New Twists on House Calls
        9. Insurance Companies Change Strategies Due to Affordable Care Act (ACA) and Rapidly Rising Costs of Care
        10. Number of Uninsured Americans Remains High
        11. Health Sharing Ministries Attract Millions of Members
        12. Massive R&D Investment Required for Development and Approval of New Blockbuster Drugs/Drug Prices Soar
        13. Fast Track Drugs Come to Market in the U.S. with FDA Cooperation
        14. Generic Drugs Have Biggest Market Share By Unit Volume, but not by Total Revenues
        15. America Pays Higher Prices for Drugs Than Other Nations/U.S. Government Launches Drug Price Negotiation and Control Powers for Medicare
        16. Biotech and Orphan Drugs Create New Revenues for Drug Firms
        17. Revolutionary New Drugs (Zepbound, Wegovy and Ozempic) Treat Obesity, Diabetes and Addiction/Show Promise for Treating Many Other Diseases
        18. Quality of Care and Health Care Outcomes Data Are Available Online, Creating a New Level of Transparency
        19. Obesity Sparks Government, School and Corporate Initiatives/Snack Foods Get Healthier
        20. Health Care Goes Offshore, Medical Tourism and Clinical Trials Continue in China, India and Elsewhere
        21. Retail Clinics, Urgent Care Centers and Employer Sites Increase Health Care Options but Suffer Challenges
        22. Health Care Industry Grows Rapidly in China, India and Mexico

        The Outlook for Health Care Technology:

        1. Health Care Technology Introduction
        2. Electronic Health Records (EHR) Digitize Patient Records at an Accelerating Pace
        3. Telemedicine and Remote Patient Monitoring Rely on Wireless
        4. Stem Cells and 3D Printing—A New Era of Regenerative Medicine Takes Shape
        5. Health Care Robotics
        6. Patients’ Genetic Profiles Plummet in Price as DNA Sequencing Technologies Advance
        7. Advances for Cancer Patients in Chemotherapy and Radiation, Including Proton Beams and IMRT
        8. Immunotherapy, ADCs, Protein Degraders and CAR-T Create Exciting New Approach to Fighting Cancers
        9. Better Imaging, including MRI, PET and 640-Slice CT, Creates Advances in Detection
        10. Artificial Intelligence (AI), Deep Learning and Machine Learning Advance into Commercial Applications, Including Health Care and Robotics

        Plunkett Research Provides In-Depth Tables for the Following Health Care Industry Statistics

        1. U.S. Health Care Industry Overview
          U.S. Health Care Industry Statistics and Market Size Overview
          Global Health Statistics, 2020-2025
          Employment in the Health Care Industry, U.S.: 2021 – August 2026
          U.S. FDA New Drug (NDA) and Biologic (BLA) Approvals, 2025
          The U.S. Drug Discovery & Approval Process
          Federal R&D & R&D Plant Funding for Health and Human Services, U.S.: Fiscal Years 2024-2026
          Research Funding for Biological Sciences, U.S. National Science Foundation Fiscal Years 2025-2027
        2. U.S. Health Care Expenditures & Costs
          The Nation’s Health Dollar: 2026 Where It Came From (Projected)
          The Nation’s Health Dollar: 2026 Where It Went (Estimated)
          National Health Expenditures & Annual Percent Change, U.S.: 2018-2034
          National Health Expenditures by Type of Expenditure with Affordable Care Act Impacts, U.S.: Selected Calendar Years, 2021-2034
          Hospital Care Expenditures & Annual Percent Change, U.S.: 2018-2034
          Nursing Home Care Expenditures & Annual Percent Change, U.S.: 2018-2034
          Home Health Care Expenditures & Annual Percent Change, U.S.: 2018-2034
          Prescription Drug Expenditures & Annual Percent Change, U.S.: 2018-2034
        3. Medicare & Medicaid
          Medicare Enrollment, 1975-2100
          Medicaid Enrollment & Expenditures for Medical Assistance Payments & Administration: Selected Years, 1966-2034
        4. U.S. Health Insurance Coverage & The Uninsured
          Number & Percent of Persons of All Ages with and without Health Insurance Coverage, U.S.: 2007-2025
          Employers’ Costs for Total Compensation and Health Insurance, by Selected Characteristics, U.S.: Selected Years, 2022-2026

        Plunkett Research, Ltd., a Houston, Texas-based market research firm, has completed its latest research on American Employers.  (See: https://www.plunkettresearch.com/industries/major-employers-jobs-market-research/).  This revised and updated data is part of our massive Plunkett Research Online subscription service, where we continuously monitor the world’s 40 most vital business sectors, including such industries as retailing, artificial intelligence, health care, sports/recreation and much, much more.  Our analysts and market research continually monitor the world’s leading industries and companies and post thorough updates yearly.

        Key Findings:

        A complete report by Plunkett Research analyzing both America’s top employers and the major trends sweeping through business and the economy that affect job seekers of all types.  THE ALMANAC OF AMERICAN EMPLOYERS is the premier guide to 500 of the largest, most successful corporate employers in the nation (those with 2,500+ employee count), their employment practices, benefits and financial performance.

        Key Features:

        • Job market trends analysis, data and competitive intelligence
        • Statistical tables
        • Employment forecasts and statistics
        • Important Contacts for Job Seekers
        • In-Depth Profiles of 500 of the largest, fastest-growing corporate employers

        Gather Key Insights, Such As:

        • How is each industry evolving?
        • How is employment being shaped by new technologies?
        • How is demand growing?
        • What are the financial results of the leading companies?
        • What are the names and titles of top executives?
        • What are the top companies and what are their revenues?

        The Almanac of American Employers and the related online Major Employers Research Center are designed to be time-saving business tools for job seekers, marketers, sales directors, consultants, and strategists seeking to understand vibrant American corporate employers.  It will also be of great use to placement, recruiting and human resources professionals, as well as professionals working in economic development, lending, and media.  This feature rich almanac includes:

        Contents, Statistics and Analysis Include:

        Plunkett Research Provides Unique Analysis of the Following Major Trends Affecting Job Seekers

        1. The U.S. Job Market Overview
        2. Cost Control Remains a Major Concern at Employers/Consolidation Through Mergers Continues
        3. The Sharing & Gig Economy’s Effect on Employment, Work Life and Careers
        4. Technology Continues to Create Sweeping Changes in the Workplace
        5. Continued Growth in Outsourcing, Including Supply Chain and Logistics Services
        6. Offshoring and the Reshoring of American Manufacturing
        7. Older Americans Will Delay Retirement and Work Longer/Many Employers Find Older Employees Desirable
        8. Employment Sectors that Will Offer an Above-Average Number of Job Opportunities

        Plunkett Research Provides In-Depth Tables for the Following Statistics

        1. U.S. Employment Statistics Overview: 2025-2026
        2. U.S. Civilian Labor Force: 1998 – August 2026
        3. Employment by Major Industry Sector: 2015, 2025 & Projected 2035
        4. Number of People Employed and Unemployed, U.S.: August 2025 vs. August 2026
        5. Employment Status of the Civilian Noninstitutional Population 16 to 24 years of Age by School Enrollment, Age, Sex, Race, and Educational Attainment: September 2026
        6. Retirement Benefits in the U.S.: Access, Participation and Take-Up Rates, March 2026
        7. Top 30 U.S. Fastest Growing Occupations By Percent Change: 2025-2035
        8. Occupations with the Largest Expected Employment Increases, U.S.: 2025-2035
        9. Occupations with the Fastest Expected Decline, U.S.: 2025-2035

        10.15.26

        Credit: iStock.com/xieyuliang

        The global automobile industry is undergoing one of the most significant transformations in its history. Electric vehicles (EVs), hybrid technology, artificial intelligence (AI), autonomous driving and growing competition from Chinese manufacturers are reshaping the market. At the same time, changing government policies, tariffs, rising manufacturing costs and evolving consumer preferences are forcing traditional automakers to reconsider their strategies.

        Worldwide automobile sales remain substantial, with approximately 91.7 million new vehicles forecast for 2025, compared to 88.3 million in 2024. U.S. automobile sales reached approximately 16.2 million vehicles in 2025. However, the industry’s future increasingly depends on manufacturers’ ability to deliver affordable, technologically advanced vehicles while maintaining profitability.

        Even more information on this industry is available!  Check out our Automobile Industry Center.

        Plunkett’s Automobile Industry eBook, latest edition.

        1. Electric Vehicle Sales Slow in the U.S. as Hybrids Gain Popularity

          One of the automobile industry’s most important trends is the slowdown in U.S. electric vehicle adoption. According to Cox Automotive, U.S. EV sales declined approximately 2% in 2025 to 1.27 million vehicles, representing 7.8% of total automobile sales.

          The expiration of federal EV purchase tax credits of up to $7,500 in September 2025 further weakened consumer demand. High vehicle prices, inadequate charging infrastructure, expensive repairs and concerns about driving range continue to discourage potential buyers.

          Major automakers have suffered enormous financial setbacks. Ford announced a $19.5 billion EV-related writedown in late 2025, while General Motors recorded a $7.1 billion charge. Stellantis announced a $26 billion restructuring charge in early 2026, and Honda reported approximately $15.7 billion in restructuring charges and writedowns.

          Consequently, manufacturers are scaling back ambitious EV production plans and redirecting investments toward more profitable vehicles.

          Meanwhile, hybrids are becoming increasingly attractive. U.S. hybrid sales increased nearly 27% in 2025, reflecting consumers’ preference for improved fuel efficiency without the charging limitations associated with fully electric vehicles. Plug-in hybrids and extended-range electric vehicles are also attracting attention as alternatives to conventional EVs.

          2. China Emerges as a Dominant Global Automotive Powerhouse

          China has become the world’s largest automobile market and one of the industry’s most formidable competitors. The China Association of Automobile Manufacturers reported record sales of 34.4 million vehicles in 2025, up from 31.44 million in 2024.

          Chinese manufacturers, particularly BYD and SAIC, are expanding aggressively into international markets with technologically advanced, competitively priced vehicles. China exported approximately 2.6 million electric vehicles and hybrids in 2025, roughly double its 2024 total.

          China’s dominance in battery manufacturing, government-supported production capacity and efficient supply chains gives its automakers substantial cost advantages. BYD, for example, offers electric and hybrid vehicles at prices significantly below many competing Western models.

          This competition is placing considerable pressure on Volkswagen, General Motors, Ford and other established manufacturers. European automakers are particularly vulnerable as Chinese brands expand throughout Europe and Southeast Asia.

          Meanwhile, India represents another important growth opportunity. Passenger vehicle sales reached approximately 4.55 million during India’s 2025-2026 fiscal year. Its expanding middle class and relatively young population offer significant long-term potential.

          Mexico also remains a major automotive manufacturing center, exporting approximately 80% of the vehicles it produces, primarily to the United States.

          3. Battery Technology and Charging Infrastructure Become Critical Priorities

          Battery innovation remains essential to the future of electric transportation. Manufacturers are investing heavily in lithium iron phosphate (LFP) batteries, sodium-ion technology, lithium-silicon materials and other advanced battery systems.

          LFP batteries offer lower costs and improved safety because they do not require expensive nickel or cobalt. Sodium-ion batteries could further reduce costs and dependence on Chinese-controlled battery supply chains.

          Companies including Tesla, Ford, Rivian, CATL and BYD are investing in battery manufacturing and research. Advanced technologies promise longer driving ranges, faster charging and improved battery durability.

          However, significant challenges remain. Public charging networks are still inadequate in many regions, while expanding EV adoption will require substantial investments in electricity generation and distribution. Growing electricity demand from AI data centers may further complicate these challenges.

          4. Autonomous Vehicles and Robotaxis Move Toward Commercial Deployment

          Autonomous driving technology is progressing from experimentation toward commercial operations. Alphabet’s Waymo, Tesla and Amazon’s Zoox are expanding driverless transportation initiatives, while Uber and Lyft are developing partnerships to incorporate robotaxis into their ride-hailing networks.

          Waymo was operating in 10 U.S. cities by early 2026. Tesla launched its robotaxi service in Austin, Texas, in June 2025, subsequently expanding its driverless operations. Uber is pursuing partnerships intended to deploy thousands of autonomous vehicles in coming years.

          AI, sophisticated cameras, sensors and advanced mapping software enable these vehicles to navigate increasingly complex driving environments.

          Autonomous commercial trucking is also advancing. Aurora Innovation began operating driverless semi-trucks on public highways, primarily transporting commercial freight between major hubs in Texas and Arizona.

          Robotaxis could substantially reduce ride-hailing operating costs by eliminating driver expenses. Over time, widespread autonomous transportation may also reduce private automobile ownership, particularly in densely populated urban areas.

          Nevertheless, safety, regulatory approval, liability and technological reliability remain important obstacles to widespread adoption.

          5. Tariffs and Manufacturing Costs Reshape Global Supply Chains

          Trade policies are becoming increasingly important to automotive manufacturers. New U.S. tariffs on imported vehicles and automotive components are raising production costs and encouraging manufacturers to reconsider global supply chains.

          Analysts estimated that tariffs could add approximately $2,300 to the cost of manufacturing a vehicle. General Motors anticipated up to $5 billion in gross tariff-related costs in 2025, while Ford expected approximately $3 billion.

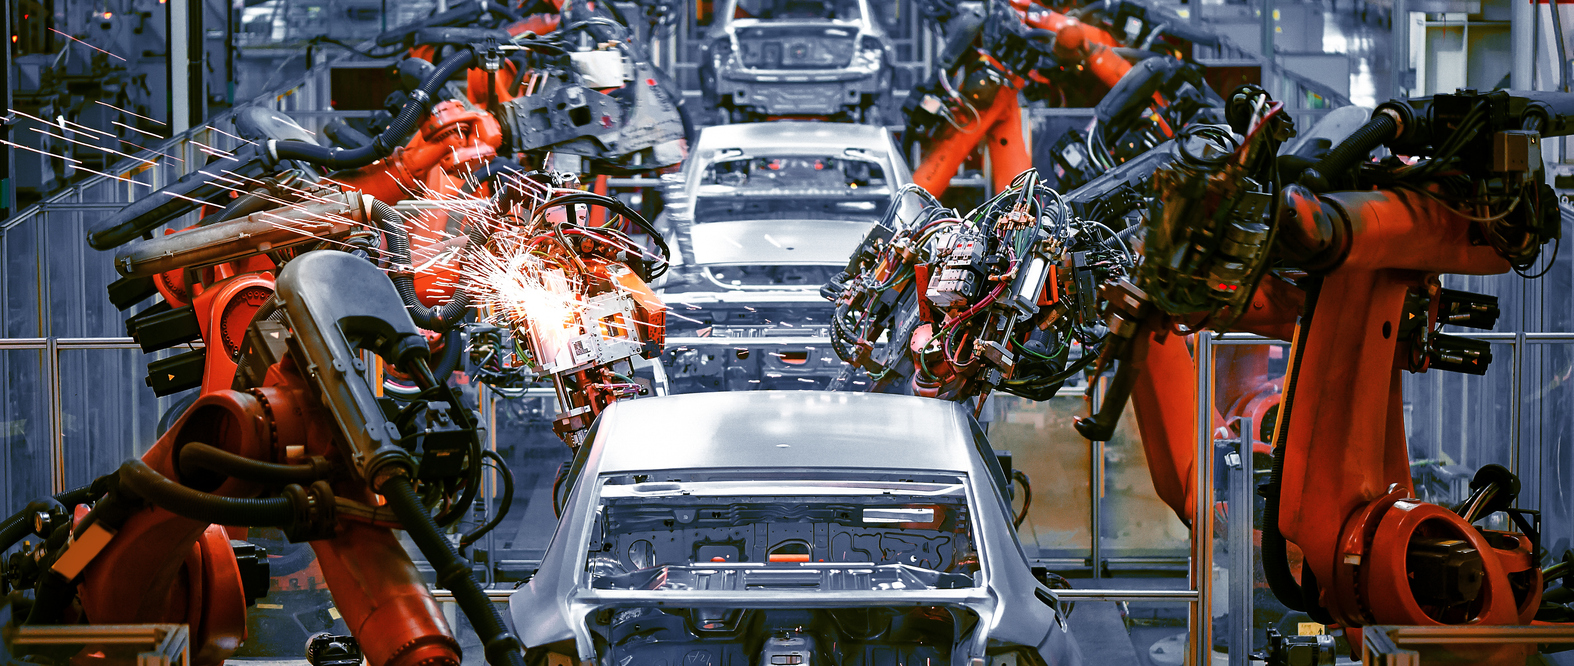
          Manufacturers are responding by investing in domestic production, automation and more flexible factories. Robotics, advanced manufacturing software and lean inventory systems are helping reduce labor requirements and improve efficiency.

          At the same time, demand for profitable pickup trucks, SUVs and crossovers remains strong. Ford and General Motors have largely abandoned traditional sedans in favor of these popular vehicle categories.

          6. Safety Technology and AI Transform Automobile Insurance

          Automobile safety continues to improve through advanced driver-assistance systems, including automatic emergency braking, adaptive cruise control, lane-keeping assistance and pedestrian detection.

          Artificial intelligence is also transforming automobile insurance. Insurers increasingly utilize telematics systems to monitor driving behavior, mileage, braking patterns and vehicle usage.

          Companies such as Progressive offer usage-based insurance programs that reward safer drivers with potentially lower premiums. However, these technologies also raise privacy concerns.

          Autonomous vehicles present additional insurance challenges. As transportation shifts toward robotaxis and shared mobility, insurers must develop new policies addressing software failures, vehicle manufacturers, fleet operators and passenger liability.

          7. Alternative Fuels and Efficiency Remain Important

          Although EVs attract considerable attention, alternative fuels continue to play important roles. Natural gas-powered trucks and buses offer potential operating cost advantages for commercial fleets. Hydrogen fuel-cell vehicles remain under development, although fueling infrastructure and hydrogen production costs present significant obstacles.

          Traditional gasoline vehicles are also becoming more efficient through lightweight materials, improved engines and advanced transmissions.

          8. The Future

          The automobile industry’s future will be defined by competition between electric vehicles, hybrids and conventional automobiles; China’s expanding global influence; rapid advances in AI and autonomous transportation; and the industry’s ability to control costs.

          Manufacturers that successfully combine affordability, technological innovation, efficient production and consumer-focused vehicle designs will be best positioned to compete in an increasingly complex global market.

          Key Concepts: Cars, trucks, economics, transportation, entrepreneurship, finance, highways, globalization, hybrids, innovation, electric vehicles (EVs), self-driving vehicles, marketing, research, tariffs

          Source: Plunkett Research, Ltd., Copyright © 2026
          Plunkett Research, Ltd., a Houston, Texas-based market research firm, has completed its latest research on the Automobile Industry.  (See: https://www.plunkettresearch.com/industries/automobiles-trucks-market-research/).  This revised and updated data is part of our massive Plunkett Research Online subscription service, where we continuously monitor the world’s 40 most vital business sectors, including such industries as retailing, artificial intelligence, health care, sports/recreation and much, much more.  Our analysts and market research continually monitor the world’s leading industries and companies and post thorough updates yearly.

          Key Findings:

          A complete market research report, including forecasts and market estimates, technologies analysis and developments at innovative firms within the Automobile Industry.  Gain vital insights that can help shape strategy for business development, product development and investments.

          Key Features:

          • Business trends analysis
          • In-depth industry overview
          • Technology trends analysis
          • Forecasts
          • Spending, investment, and consumption discussions
          • In-depth industry statistics and metrics
          • Industry employment numbers

          Additional Key Features Include:

          Industry Glossary

          Industry Contacts list, including Professional Societies and Industry Associations

          Profiles of industry-leading companies

          • U.S. and Global Firms
          • Publicly held, Private and Subsidiaries
          • Executive Contacts
          • Revenues
          • For Public Companies: Detailed Financial Summaries
          • Statistical Tables

          Key Questions Answered Include:

          • How is the industry evolving?
          • How is the industry being shaped by new technologies?
          • How is demand growing in emerging markets and mature economies?
          • What is the size of the market now and in the future?
          • What are the financial results of the leading companies?
          • What are the names and titles of top executives?
          • What are the top companies and what are their revenues?

          This feature-rich report covers competitive intelligence, market research and business analysis—everything you need to know about the Automobile Industry.

          Plunkett Research Provides Unique Analysis of the Following Major Trends Affecting the Automobile Industry

          1. Major Trends Affecting the Automobile Industry
          2. Automobile Industry Introduction
          3. U.S. Auto Manufacturers Ford, Stellantis and GM Compete Head-On with Foreign Manufacturers
          4. U.S. Electric Vehicle (EV) Subsidies Expired in 2025/U.S. Auto Manufacturers Incurred Massive EV Losses and Writedowns
          5. Electric Cars (EVs) and Plug-in Hybrids (PHEVs) Spur Changes at Auto Makers
          6. Major Technology Research in Batteries/Major Investments in Battery Factories and Power Storage
          7. Natural Gas Power Provides An Alternative to EVs, Particularly in Commercial Trucks and Buses
          8. Fuel Efficiency Continues to Improve
          9. Ethanol Production Is Massive for Fuel Additives
          10. Cellulosic Ethanol Makes Slow Commercial Progress
          11. Fuel Cell and Hydrogen Power Research Continue/Fuel Cell Cars Enter Market
          12. China Is the World’s Largest Auto Market/ Becomes a Major Auto Exporter and EV Supply Chain Player
          13. India Has a Significant Automobile Market, with Great Long-Term Potential
          14. Mexico Is a Leading Automotive Maker and Exporter
          15. Focus on Safety Improvements by Automakers
          16. Insurance Underwriting Uses Artificial Intelligence (AI)/Policy Holders Allow Their Habits to Be Tracked for Lower Insurance Rates
          17. Uber, Lyft and Didi Dominate the Car on Demand (Ride Hailing) Industry
          18. Self-Driving, Autonomous Cars Receive Massive Investments in Research and Development Worldwide
          19. Gig Economy and Self-Driving Cars Pose Insurance Challenges and Underwriting Opportunities

          Plunkett Research Provides In-Depth Tables for the Following Automobile Industry Statistics

          1. Automobile Industry Statistics and Market Size Overview
          2. General Motors Corporation Overview
          3. Ford Motor Company Overview
          4. Volkswagen Group Overview
          5. Toyota Motor Corporation Overview
          6. Mercedes-Benz Group Overview
          7. Hyundai Motor Group Overview
          8. Honda Motor Co. Overview
          9. Licensed Drivers, Vehicle Registrations & Resident Population, U.S.: 1960-2024
          10. Highest Fuel Economy by Vehicle Class: 2026 Model Year
          11. Lowest Fuel Economy by Vehicle Class: 2026 Model Year
          12. Gross Output in the Motor Vehicles & Transportation Equipment Manufacturing Industries: Selected Years, 2018-2024
          13. Personal Transportation Expenditures, U.S.: 2019-2025
          14. Average Miles Per Gallon vs. Horsepower, U.S.: 1975-2024
          15. Motor Vehicle Traffic Accidents in the U.S. by Type of Vehicle & Person: 2015 – 2024
          16. Value of Imports of Vehicles to the U.S.: 2019-2025
          17. Value of Exports of U.S. Vehicles: 2019-2025
          18. Occupational Employment and Wages for Automotive Service Technicians and Mechanics: May 2025
          19. Employment in the Automobile Industry, U.S.: 2020 – July 2026

          10.5.26

          Credit: iStock.com/rozdemir01

          The manufacturing, automation and robotics industry is entering one of its most significant periods of change in decades. Artificial intelligence (AI), advanced robotics, shifting supply chains, tariffs, labor shortages and new production technologies are transforming factories worldwide. At the same time, manufacturers are reconsidering where products should be made and how much human labor future factories will require.

          The scale of the industry is enormous. Worldwide manufacturing value added totaled an estimated $16.83 trillion in 2024. Yet the nature of that manufacturing is changing rapidly as companies invest in robotics and automation to increase productivity, improve quality and respond to shortages of skilled workers. The worldwide installed base of operational industrial robots was expected to reach approximately 5.9 million by the end of 2025.

          Even more information on this industry is available!  Check out our Manufacturing Industry Center.

          Plunkett’s Manufacturing, Automation & Robotics Industry eBook, latest edition.

          1. AI Is Transforming Factory Automation

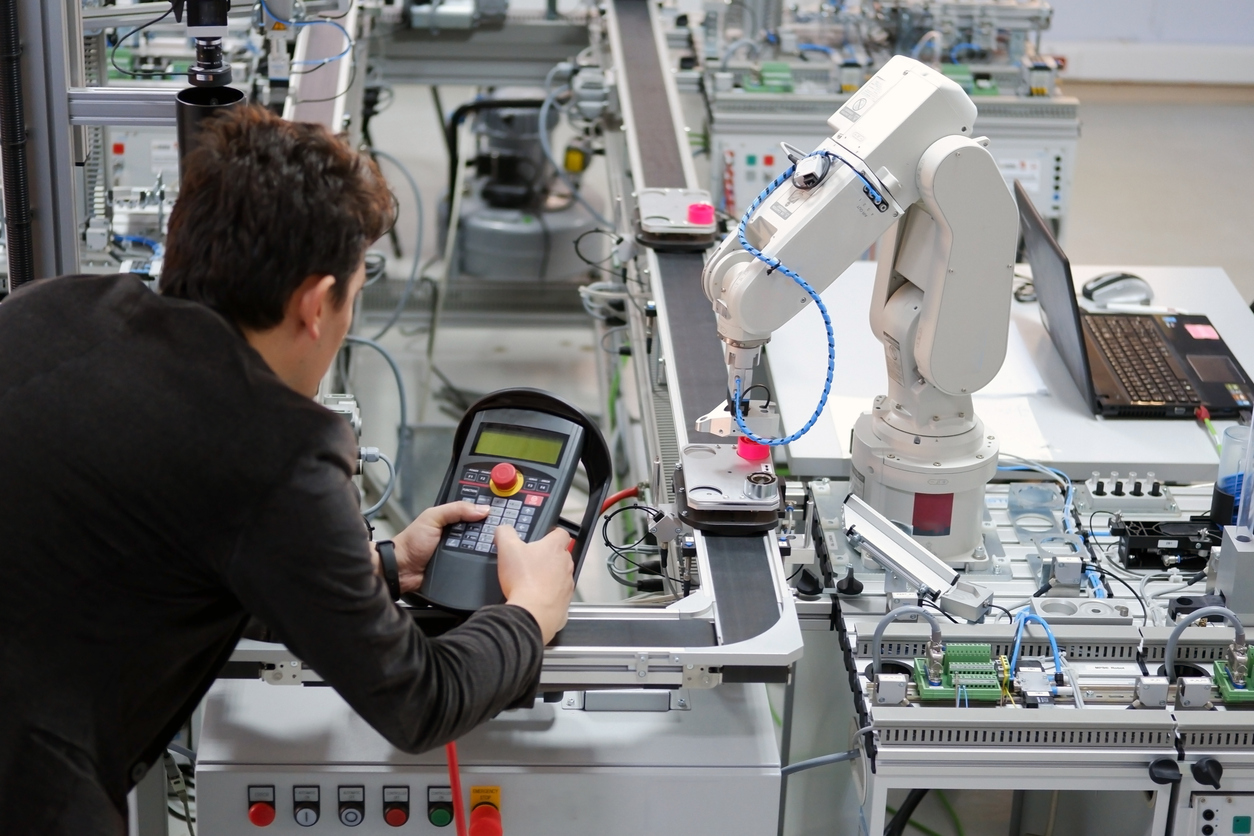
            One of the biggest trends is the convergence of AI, machine learning and robotics. Industrial robots have been used for decades for welding, painting, assembly and materials handling. However, AI is making robots more capable, adaptable and autonomous. AI-enabled systems can analyze production data, detect quality problems, optimize workflows and help predict when machinery needs maintenance.

            Factories are also becoming increasingly connected. Computer-aided design and manufacturing systems can link product development directly to computer-controlled production equipment, while robots can manage warehouses and deliver components to production lines as needed. This combination of software, AI, sensors and robotics is creating increasingly sophisticated smart factories.

            Importantly, automation is no longer simply about replacing employees. Manufacturers increasingly need robots to achieve productivity gains while coping with rising wages and shortages of available workers. This means manufacturing output may grow substantially faster than manufacturing employment. The U.S., for example, employed approximately 12.7 million manufacturing workers as of mid-2026, compared with 19.1 million in 1980.

            2. Cobots Expand the Reach of Robotics

            Another important development is the rapid adoption of collaborative robots, or cobots. These machines are designed to work alongside people rather than being separated from them by cages or other barriers. Cobots tend to be flexible and relatively easy to program, making automation practical for a broader range of manufacturing and warehouse operations.

            The potential productivity gains are significant. Data center infrastructure manufacturer Tate operates 58 Hirebotics Cobot Welder systems that achieved a 12-fold increase in output per welder. Sanofi has deployed Universal Robots cobots for end-of-line packaging, cutting working time by 10% while allowing production lines to operate with fewer manual workers.

            Robots are likewise spreading throughout warehouses and logistics operations. Automated systems can retrieve products, transport materials and help fulfill orders, making robotics an increasingly important component of the entire supply chain rather than simply the factory floor.

            3. Humanoid Robots Emerge as the Next Frontier

            Perhaps no development is generating more attention than the humanoid robot. These machines have legs, arms and hands that enable them to operate in environments originally designed for humans. AI-powered humanoids eventually could perform a wide variety of manufacturing, logistics and warehouse tasks without factories having to be redesigned around conventional fixed robots.

            China has established a particularly strong position in this emerging industry. Its advantages include extensive government support, enormous manufacturing capacity and an existing supply network for motors, gears, sensors, batteries and precision components. According to data cited in the chapter, Chinese manufacturers accounted for the majority of approximately 13,000 humanoid robots shipped globally in 2025. China is home to dozens of companies developing humanoids, including AgiBot, Unitree and UBTech.

            Automotive manufacturers are becoming important testing grounds. BMW, Hyundai, Toyota and Mercedes-Benz are among companies testing humanoids for moving parts, transporting heavy loads and assisting with assembly. Airbus ordered UBTech’s Walker S2 for manufacturing applications in early 2026.

            China’s advantage extends to conventional automation. By 2026, China was producing approximately 50% of newly installed industrial robots worldwide and had reached a robot density of 470 units per 10,000 workers. Automation is particularly important because China’s working-age population is shrinking while factory wages have increased.

            4. Manufacturing Supply Chains Are Being Reconfigured

            Globalization is not ending, but manufacturing supply chains are becoming more diversified. Rising Chinese wages, geopolitical tensions and the supply-chain disruptions experienced during the pandemic convinced many multinational companies that relying too heavily on one manufacturing country creates substantial risks.

            As a result, Vietnam, India, Bangladesh and other lower-cost nations are attracting production. China’s share of U.S. imports dropped from nearly 22% in 2016 to about 9% in 2025. At the same time, Chinese manufacturers themselves are moving toward higher-value products, including industrial robots, semiconductor equipment and sophisticated machinery.

            Mexico is another major beneficiary. Its proximity to the U.S., transportation infrastructure and trade relationship with the U.S. and Canada make it attractive for nearshoring, in which manufacturers locate production closer to their primary customers.

            Reshoring is also bringing some production back to the United States. Approximately 244,000 jobs were reshored in 2025, according to figures cited in the chapter. Lower relative U.S. energy costs, improved productivity and increasingly cost-effective automation can make domestic production more competitive. John Deere expanded excavator production in North Carolina in 2026, while Caterpillar and GE Aerospace have been expanding U.S. manufacturing capacity and local supply chains.

            5. Tariffs Create New Costs and Uncertainty

            Tariffs are simultaneously encouraging companies to reconsider overseas sourcing and creating significant challenges for manufacturers. Duties on imported materials and components can raise production costs, disrupt established supply chains and force manufacturers either to absorb additional expenses or pass them to customers.

            The uncertainty itself can be consequential. Some companies are delaying production and capital-investment decisions while waiting for greater clarity about tariff policies. Despite increased tariffs, the Kearney Reshoring Index remained negative in 2025, illustrating that bringing manufacturing home is more complicated than simply raising the cost of imports.

            6. The Future

            Technologies such as 3-D printing, advanced software, high-speed networks and additive manufacturing are reinforcing the transformation. 3-D printing can dramatically reduce prototyping and product-development costs, while digital design systems make it possible to move more quickly from an idea to automated production.

            The result is a fundamentally different manufacturing landscape. Future competitiveness will increasingly depend on the combination of AI, robotics, skilled engineering talent, resilient supply chains and flexible production. Factories will become more automated and productive, while cobots and humanoids will increasingly work alongside people. Meanwhile, manufacturers will continue balancing the efficiencies of global production against the security of nearshoring and reshoring.

            Key Concepts:  Manufacturing, factories, robotics, factory automation, auto makers, China, machine tools, additive (3D) manufacturing, OEM – Original Equipment Manufacturing, ODM – Original design manufacturing, artificial intelligence (AI), tariffs, humanoid robots, cobots

            Source: Plunkett Research, Ltd., Copyright © 2026
            Plunkett Research, Ltd., a Houston, Texas-based market research firm, has completed its latest research on the Manufacturing, Automation & Robotics Industry.  (See: https://www.plunkettresearch.com/industries/manufacturing-automation-robotics-market-research/).  This revised and updated data is part of our massive Plunkett Research Online subscription service, where we continuously monitor the world’s 40 most vital business sectors, including such industries as retailing, artificial intelligence, health care, sports/recreation and much, much more.  Our analysts and market research continually monitor the world’s leading industries and companies and post thorough updates yearly.

            Key Findings:

            A complete market research report, including forecasts and market estimates, technologies analysis and developments at innovative firms within the Manufacturing, Automation & Robotics Industry.  Gain vital insights that can help shape strategy for business development, product development and investments.

            Key Features:

            • Business trends analysis
            • In-depth industry overview
            • Technology trends analysis
            • Forecasts
            • Spending, investment, and consumption discussions
            • In-depth industry statistics and metrics
            • Industry employment numbers

            Additional Key Features Include:

            Industry Glossary

            Industry Contacts list, including Professional Societies and Industry Associations

            Profiles of industry-leading companies

            • U.S. and Global Firms
            • Publicly held, Private and Subsidiaries
            • Executive Contacts
            • Revenues
            • For Public Companies: Detailed Financial Summaries
            • Statistical Tables

            Key Questions Answered Include:

            • How is the industry evolving?
            • How is the industry being shaped by new technologies?
            • How is demand growing in emerging markets and mature economies?
            • What is the size of the market now and in the future?
            • What are the financial results of the leading companies?
            • What are the names and titles of top executives?
            • What are the top companies and what are their revenues?

            This feature-rich report covers competitive intelligence, market research and business analysis—everything you need to know about the Manufacturing, Automation & Robotics Industry.

            Plunkett Research Provides Unique Analysis of the Following Major Trends Affecting the Manufacturing, Automation & Robotics Industry

            1. Major Trends Affecting the Manufacturing, Automation & Robotics Industry
            2. Introduction to the Manufacturing, Automation & Robotics Industry
            3. Industrial Robots and Factory Automation Advance Through Artificial Intelligence (AI)
            4. Service Robots/Cobots Are Boosting Efficiencies in Warehouses and More
            5. China Dominates Race to Develop Humanoid Robots
            6. Tariffs Impact Manufacturing of All Types/Imports from the EU, China, Mexico and India Affected
            7. U.S. Electric Vehicle (EV) Subsidies Expire in 2025/U.S. Auto Manufacturers Change Strategies
            8. Global Growth in Manufacturing and Trade Require Investment by Emerging Nations
            9. Introduction to the Outsourcing & Offshoring Industry
            10. Pros and Cons of Outsourcing & Offshoring
            11. Nearshoring and Reshoring Keep Operations Closer to Home
            12. U.S. Apparel and Textile Jobs Reshore to Some Extent
            13. Vietnam, India and Other Countries Gain Manufacturing Market Share/Tariffs Alter Market Significantly
            14. The Vast Majority of Shoes Sold in the U.S. Are Made Elsewhere
            15. 3-D Printing and Robotics Revolutionize Manufacture of Shoes and Fabrics
            16. Original Design Manufacturing (ODM) Adds Value to Contract Electronics Manufacturing
            17. Trends in Manufacturing, such as Original Design Manufacturers (ODMs), Lead to Collaboration and Consulting-Like Services
            18. 3PL Logistics Services and Supply Chain Management Services Evolve and Consolidate
            19. Manufacturers Focus on High Performance Plastics and Specialty Chemicals
            20. Refineries Along with Chemicals and Plastics Plants Expand in the U.S.
            21. Telecom Equipment Makers Face Intense Competition from Manufacturers in China
            22. Boeing and Airbus Compete for New Orders
            23. U.S. Auto Manufacturers Ford, Stellantis and GM Compete Head-On with Foreign Manufacturers
            24. India Has a Significant Automobile Market, with Great Long-Term Potential
            25. Mexico Is a Leading Automotive Maker and Exporter
            26. Designers and Manufacturers Bypass the Middleman with Direct-to-Consumer Online Business Models
            27. Artificial Intelligence (AI), Deep Learning and Machine Learning Advance into Commercial Applications, Including Health Care and Robotics
            28. The Internet of Things (IoT) in Factories, Robotics and Equipment
            29. Health Care Robotics
            30. Robotics in Retailing and Ecommerce Fulfillment
            31. Chips Built with Low Nanometer, High Density Design/Faster Chips Power Artificial Intelligence (AI)/Processor Development Booms

            Plunkett Research Provides In-Depth Tables for the Following Manufacturing, Automation & Robotics Industry Statistics

            1. Overview of the Manufacturing, Automation & Robotics Industry
              1. Manufacturing, Automation & Robotics Industry Statistics and Market Size Overview
              2. Sales & Net Income After-Tax, U.S. Manufacturing Corporations: 2015- 2nd Quarter 2026
              3. Sales & Operating Profits, U.S. Manufacturing Corporations, by Industry: 4th Quarter 2025- 2nd Quarter 2026
            2. Output & Employment
              1. Value Added to U.S. Economy by Manufacturing Sector, as a Percentage of GDP: 1997-2025
              2. Employment in the U.S. Manufacturing Sector, as a Percentage of all Private Industry Employment: 1950 – July 2026
              3. Employment in the U.S. Manufacturing Sector, by Industry: 2020 – July 2026
              4. Manufacturing Output vs. Employment, U.S.: 1980- August 2026
              5. Gross Output in the Wood & Nonmetallic Mineral Products Manufacturing Industries: Selected Years, 2019-2024
              6. Gross Output in the Primary Metals & Fabricated Metal Products Manufacturing Industries: Selected Years, 2019-2024
              7. Gross Output in the Machinery Manufacturing Industry, U.S.:Selected Years, 2019-2024
              8. Gross Output in the Computer & Electronic Product Manufacturing Industries: Selected Years, 2019-2024
              9. Gross Output in the Electrical Equipment, Appliances & Components Manufacturing Industries: Selected Years, 2019-2024
              10. Gross Output in the Motor Vehicles & Transportation Equipment Manufacturing Industries: Selected Years, 2019-2024
              11. Gross Output in the Motor Vehicles & Transportation Equipment Manufacturing Industries: Selected Years, 2019-2024
              12. Gross Output in the Textile & Apparel Manufacturing Industries, U.S.: Selected Years, 2019-2024
              13. Gross Output in the Chemicals, Plastics & Rubber Products Manufacturing Industries, U.S.: Selected Years, 2019-2024
            3. Shipments
              1. Annual Value of Manufacturers’ Shipments for Industry Groups, U.S.: 2019-2025
            4. Exports
              1. Value of Exports of All Manufactured Goods, U.S.: 2019 – 2025
              2. Exports of Durable & Nondurable Manufactured Goods, U.S.: 2019 – 2025
              3. Value of Exports of U.S. Vehicles: 2020-2025
              4. Exports, Imports & Trade Balance of Computers & Electronic Products, U.S.: 2019-2025
              5. Exports, Imports & Trade Balance of Chemicals, U.S.: 2019 – 2025
              6. Exports, Imports & Trade Balance of Chemicals, U.S.: 2019 – 2025
              7. Exports, Imports & Trade Balance of Chemicals, U.S.: 2019 – 2025

                  9.23.26

                  Credit: iStock.com/ugurhan

                  The airline, hotel and travel industry is undergoing broad transformation as companies adapt to changing consumer tastes, new technologies and increasingly intense competition. The global travel and tourism sector supported about 366 million jobs in 2025, illustrating the industry’s enormous economic significance. Across airlines, hotels, cruises and travel booking, some of the most important trends are the growth of premium services, artificial intelligence, more efficient transportation, digital customer relationships, experiential tourism and new forms of lodging.

                  Even more information on this industry is available!  Check out our Travel Industry Center.

                  Plunkett’s Airline, Hotel & Travel Industry eBook, latest edition.

                  1. The premiumization of air travel.

                    Airlines are placing greater emphasis on business class, premium economy, extra-legroom seats and airport lounges rather than competing primarily on inexpensive economy seats. Scheduled U.S. domestic business- and first-class seats in 2026 were 27% above January 2020 levels, compared with a 10% increase in economy seats. Airlines have found that many consumers are willing to pay substantially more for comfort, convenience and better service.

                    2. Airlines are expanding their reliance on ancillary fees and loyalty programs.

                    Revenue from checked baggage, preferred seats, food, beverages and other optional services has become increasingly important. Carriers are also generating substantial revenue from relationships with credit card companies and frequent flyer programs. Southwest Airlines illustrates how low-cost and legacy business models are converging. The airline ended its longstanding free-bag policy for most travelers, adopted assigned seating and introduced additional premium options.

                    The distinction between discount carriers and traditional airlines is consequently becoming less clear. Budget airlines are adding premium products and international routes, while legacy carriers offer basic economy products in order to compete on price. This creates a travel market in which airlines increasingly serve very different customers on the same aircraft—from highly price-conscious travelers to passengers willing to pay large premiums for business-class comfort.

                    3. Aircraft efficiency and technology are transforming aviation.

                    Airlines continue replacing older planes with more fuel-efficient aircraft. Boeing’s 787 Dreamliner and Airbus’ A350 and A320neo families illustrate the industry’s emphasis on lightweight materials, advanced engines, longer range and improved passenger comfort. Modern aircraft also feature larger windows, improved cabin humidity and enhanced entertainment systems. Boeing and Airbus aircraft are dramatically more fuel-efficient per passenger mile than earlier generations, while hybrid-electric aircraft are being developed for possible service during the late 2020s and early 2030s.

                    Longer-term technologies could change aviation even more dramatically. Hydrogen-electric aircraft are under active development, with companies such as ZeroAvia working with major airlines on zero-emission propulsion systems. Supersonic flight is also attracting renewed investment. Boom Supersonic is developing its Overture aircraft, while other companies are pursuing alternative high-speed designs. These projects remain technologically and economically challenging, but they illustrate the industry’s search for both faster and more sustainable transportation.

                    4. Luxury, personalization and distinctive experiences are becoming major competitive tools in the hotel industry.

                    Affluent travelers continue to support strong demand for luxury hotels, resorts and travel experiences. At the same time, hotels are diversifying their offerings to reach very different market segments. Extended-stay properties, micro-hotels, hostels and alternative accommodations provide lower-cost or more flexible options, while upscale operators compete through highly personalized service and amenities.

                    Extended-stay lodging is an especially important growth segment. Marriott, Hilton and Hyatt are investing in properties that combine hotel services with apartment-like features such as kitchens, laundry facilities and larger living spaces. These hotels appeal to families as well as consultants, engineers, construction workers and other travelers who may remain in a city for weeks or months. The attached report also highlights continued interest in smaller rooms and “pod” concepts aimed at travelers who place location and price above space.

                    5. Hotels are becoming more localized and experience driven.

                    Travelers increasingly seek local foods, beverages, cultural experiences, outdoor activities and distinctive surroundings. Such experiences also work particularly well in an era dominated by social media, reviews and photo sharing. Hotels therefore have an incentive to create memorable settings and experiences that guests will promote themselves online.

                    6. Control of the customer relationship.

                    Online travel agencies provide travelers with convenient ways to compare hotels, flights and prices, but they can charge hotels commissions ranging from roughly 12% to 25%. Hotel companies therefore have powerful incentives to encourage customers to book directly through their own websites and apps. Loyalty points, member discounts and best-price guarantees are important weapons in this competition.

                    Mobile technology strengthens those direct relationships. Hotel apps increasingly support check-in, check-out, electronic room keys, concierge services, room-service orders and other functions. These tools provide convenience to guests while giving hotel companies more opportunities to build loyalty and gather information about customer preferences.

                    7. Artificial intelligence (AI) may become one of the industry’s most consequential technologies.

                    Travelers can use AI to compare destinations, plan itineraries and make booking decisions. Travel providers, meanwhile, can use AI for real-time pricing of hotel rooms and airline seats, route planning, maintenance and personalized recommendations. The result could be increasingly individualized travel experiences in which prices, offers and itineraries are adjusted to individual customers and changing demand.

                    8. Alternative accommodations are a disruptive force.

                    Airbnb, Vrbo and other platforms have expanded the choices available to travelers and placed additional competitive pressure on conventional hotels. Traditional hotel companies are responding with their own vacation-rental products, while platforms that began with home rentals are increasingly expanding into other travel services. The boundaries between hotels, vacation rentals and travel platforms are therefore becoming less distinct.

                    9. Cruising continues to expand while becoming increasingly segmented.

                    Large ships provide resort-style entertainment and economies of scale, while small luxury, expedition and river cruises target travelers willing to pay more for intimacy, personalized service and access to unusual destinations. Expedition cruising has expanded into destinations such as Antarctica and the Galapagos. Luxury cruise passenger numbers are expected to rise from 1.2 million in 2024 to 1.5 million by 2028, with growth projected to outpace the broader cruise industry.

                    10. The future.

                      Taken together, these trends reveal a travel industry increasingly organized around premium experiences, personalization, technology and choice. Airlines are monetizing comfort, hotels are selling distinctive experiences rather than simply rooms, digital platforms are competing for control of the traveler, and cruise operators are developing products for nearly every market niche. The companies that adapt successfully will increasingly compete not simply on transportation or accommodation, but on the complete experience surrounding the journey.

                      Key Concepts:  Airlines, business, hotels, economics, resorts, entrepreneurship, finance, travel, globalization, tourism, innovation, investing, marketing, cruises, trains, AI

                      Source: Plunkett Research, Ltd., Copyright © 2026
                      Plunkett Research, Ltd., a Houston, Texas-based market research firm, has completed its latest research on the Airline, Hotel & Travel Industry.  (See: https://www.plunkettresearch.com/industries/travel-tourism-market-research/).  This revised and updated data is part of our massive Plunkett Research Online subscription service, where we continuously monitor the world’s 40 most vital business sectors, including such industries as retailing, artificial intelligence, health care, sports/recreation and much, much more.  Our analysts and market research continually monitor the world’s leading industries and companies and post thorough updates yearly.

                      Key Findings:

                      A complete market research report, including forecasts and market estimates, technologies analysis and developments at innovative firms within the Airline, Hotel & Travel Industry.  Gain vital insights that can help shape strategy for business development, product development and investments.

                      Key Features:

                      • Business trends analysis
                      • In-depth industry overview
                      • Technology trends analysis
                      • Forecasts
                      • Spending, investment, and consumption discussions
                      • In-depth industry statistics and metrics
                      • Industry employment numbers

                      Additional Key Features Include:

                      Industry Glossary

                      Industry Contacts list, including Professional Societies and Industry Associations

                      Profiles of industry-leading companies

                      • U.S. and Global Firms
                      • Publicly held, Private and Subsidiaries
                      • Executive Contacts
                      • Revenues
                      • For Public Companies: Detailed Financial Summaries
                      • Statistical Tables

                      Key Questions Answered Include:

                      • How is the industry evolving?
                      • How is the industry being shaped by new technologies?
                      • How is demand growing in emerging markets and mature economies?
                      • What is the size of the market now and in the future?
                      • What are the financial results of the leading companies?
                      • What are the names and titles of top executives?
                      • What are the top companies and what are their revenues?

                      This feature-rich report covers competitive intelligence, market research and business analysis—everything you need to know about the Airline, Hotel & Travel Industry.

                      Plunkett Research Provides Unique Analysis of the Following Major Trends Affecting the Airline, Hotel & Travel Industry

                      1. Major Trends Affecting the Airline, Hotel & Travel Industry
                      2. Introduction to the Travel Industry
                      3. Discount Airlines Compete with Legacy Airlines, but the Differences Are Beginning to Blur
                      4. Major Airlines Change Strategy, Charge Fees
                      5. Business Class/Premium Economy Are Big Money Makers
                      6. Private Jet Sharing and Rentals Are Big Business/Semi-Private Airlines Compete
                      7. Boeing and Airbus Compete for New Orders
                      8. New Aircraft Designs Offer Greater Passenger Comfort/More Efficient Engines
                      9. Supersonic Jets Fly Again
                      10. Hydrogen and Electric Powered Airplanes Are Under Research and Development
                      11. Airports Expand
                      12. China Makes Immense Investments in Railroads, Highways, Airports & Silk Road
                      13. Online Travel Agencies (OTAs)/Hotels Fight to Keep Control of the Customer
                      14. Ecotourism, Sustainable Tourism, Adventure Tourism and Volunteerism Gained Popularity as Certification Standards Are Set
                      15. Luxury Hotel Chains Expanded Globally
                      16. What Millennials and Mobile-Savvy Consumers Want as Tourists and Travelers
                      17. Hotels Target Young Customers with Strategies Ranging from Micro Rooms and Hostels, to Hip Hotels that Encourage Mingling to Fitness Options
                      18. Localization Drives Hotel Features, Marketing
                      19. Dog-Friendly Hotels Gain Market Share
                      20. Sharing Economy Gains Market Share in Travel with Online Sites Like Airbnb, Vrbo and Many Global Competitors
                      21. Cruise Industry Enjoys High Occupancy and Launches New Ships
                      22. Small Cruise Ships Feature Adventure, Luxury, Intimacy or Access to More Places
                      23. River Cruise Lines Reap the Benefits of Low Capital Investment and High Fares
                      24. Chinese Tourists Create Growth Opportunities for the Cruise and Hotel Industries
                      25. New Technologies Show Promise for Port and Airport Security
                      26. High Speed Passenger Trains, Including Maglev, Advance in China and Europe
                      27. U.S. Passenger Train Projects Receive Funding, Including Light Rail and Brightline in Florida
                      28. Aging Baby Boomers Will Cause Significant Changes in the Leisure Sector, Including Sports and Activity-Based Travel
                      29. The Future of Travel

                      Plunkett Research Provides In-Depth Tables for the Following Airline, Hotel & Travel Industry Statistics

                      1. Airline, Hotel & Travel Industry Statistics and Market Size Overview
                      2. Air Carrier Traffic Statistics, U.S.: 2000 – 2025
                      3. Consolidation in U.S. Airlines
                      4. U.S. Airline Passenger Activity: 2010-2046
                      5. Top Regions of U.S. Residents Traveling Abroad (Outbound): 2024-2025
                      6. Top 10 U.S. Airlines & Airports Ranked by 2026 System Scheduled Enplanements
                      7. Cruise Line Industry Overview, U.S.: 2017-2025
                      8. Estimated U.S. Hotel & Accommodations Sector Quarterly Revenues: 2023 – 2025
                      9. Employment in the Airline, Hotel & Travel Industry, U.S.: 2020 – June 2026
                      10. Quarterly U.S. Scheduled Service Passenger Airlines Financial Reports: 1st Quarter 2025-1st Quarter 2026
                      11. Total Scheduled U.S. International Passenger Traffic, U.S. Commercial Air Carriers: 2010-2046

                      9.21.26

                      Credit: iStock.com/skynesher

                      The biotechnology, pharmaceuticals and genetics industry is entering one of the most consequential periods in its history. Artificial intelligence, gene editing, dramatically cheaper DNA sequencing, personalized medicine, new cancer treatments and a booming market for obesity drugs are changing both the science and economics of medicine. At the same time, drug companies face intense pressure from soaring research costs, patent expirations, biosimilar competition and government efforts to restrain prices.

                      Even more information on this industry is available!  Check out our Biotech Industry Center.

                      Plunkett’s Biotech, Pharmaceuticals & Genetics Industry eBook, latest edition.

                      1. The rapid integration of artificial intelligence into pharmaceutical research and development.

                        Drug companies are using AI for target identification, molecular design, protein analysis, clinical-trial optimization and patient selection. AI systems can analyze enormous quantities of biological and chemical data and run simulations continuously, potentially reducing the time and expense involved in finding promising new compounds. The technology is also being used to identify new uses for medicines that have already received regulatory approval. AI is therefore shifting from an experimental tool into a core part of pharmaceutical R&D.

                        2. The extraordinary growth of GLP-1 obesity and diabetes treatments

                        Novo Nordisk’s Wegovy and Ozempic and Eli Lilly’s Zepbound helped demonstrate that drugs acting on GLP-1 pathways could produce major weight loss while also treating diabetes. Researchers are now exploring potential benefits involving cardiovascular, kidney and liver disease, sleep apnea, Alzheimer’s disease and even alcohol or drug addiction.

                        The market is also becoming more competitive and convenient. Newer oral alternatives reduce the need for injections, while expanded manufacturing capacity and competition are putting downward pressure on prices. The report notes that the global market opportunity remains immense and that these treatments could rank among the highest-grossing pharmaceuticals in history.

                        3. Genetics and personalized medicine evolve.  

                        The cost of sequencing a nearly complete human genome has fallen from roughly $100 million in 2001 to about $100 to $200 today. That extraordinary decline makes it increasingly practical to analyze patients’ genetic profiles and select drugs based on how an individual is likely to respond. Genetic information may also help physicians determine appropriate dosages and identify mutations that are driving disease.

                        4. Gene therapy and CRISPR gene editing make great strides.

                        Gene therapies attempt to correct defective genes or introduce functioning copies, potentially attacking the underlying cause of an illness rather than simply treating symptoms. CRISPR provides scientists with an increasingly precise way to edit specific portions of DNA. Research is also moving toward in vivo treatments that edit genes directly inside the body.

                        Perhaps even more significant commercially, genetic medicine may eventually move beyond extremely rare diseases. Researchers are exploring epigenetic approaches that alter gene activity without permanently cutting DNA, including therapies aimed at cardiovascular disease. If successful, genetic medicines could address much larger patient populations and become a major part of mainstream medicine.

                        5. mRNA technology is moving beyond its pandemic-era role.

                        COVID-19 vaccines demonstrated that mRNA platforms could be designed and produced rapidly. Pharmaceutical developers are now applying the technology to cancer and personalized medicine. The report highlights 2026 Phase 3 results from Moderna and Merck involving an individualized mRNA treatment combined with Keytruda for advanced melanoma. Tumor material is sequenced and used to create a customized vaccine that teaches the patient’s immune system to recognize specific cancer cells.

                        6. Cancer treatment becomes more targeted and personalized.

                        Immunotherapies encourage the immune system to attack malignant cells, while CAR-T therapies re-engineer a patient’s white blood cells. Antibody-drug conjugates deliver cancer-killing agents more directly to tumors. Genetic sequencing is simultaneously helping physicians determine which therapies are likely to work for particular patients. These techniques represent a fundamental shift away from treating cancers solely according to where they originate in the body and toward treating them according to their underlying biological and genetic characteristics.

                        7. Large pharmaceutical companies increasingly rely on smaller biotech firms for innovation.

                        Patent expirations threaten established blockbusters, encouraging large firms to acquire, license or partner with companies that possess promising drug pipelines. Rather than relying only on gigantic corporate mergers, pharmaceutical companies are increasingly making smaller acquisitions and licensing deals that spread risk across multiple technologies and drug candidates.

                        8. China emerges as a major source of new drugs rather than merely a manufacturing base or sales market.

                        Western and Japanese pharmaceutical companies entered 70 deals with Chinese biotech firms during 2025, paying a cumulative $5.6 billion for rights to promising molecules. Major 2026 agreements included AstraZeneca’s deal with CSPC Pharmaceutical and Bristol Myers Squibb’s partnership with Hengrui Pharma.

                        9. Innovation is extremely expensive while governments and consumers increasingly demand lower drug prices.

                        U.S. prescription-drug spending was forecast at $561.5 billion in 2026, while Plunkett Research estimated the global pharmaceuticals market at roughly $1.9 trillion. Drug development can require investments approaching or exceeding $1 billion per successful therapy, while many experimental compounds never reach the market.

                        Pressure will intensify as major patents expire, biosimilars become more common and Medicare exercises new drug-price negotiating powers. Generics already represented about 90% of U.S. prescriptions by volume in 2025, while major products such as Keytruda face eventual patent expiration.

                        10. The future.

                          Taken together, these developments point toward an industry that is becoming increasingly AI-enabled, genetically targeted, personalized, global and partnership-driven. The scientific opportunities are extraordinary, but so are the financial and regulatory challenges. Companies that can combine breakthrough biology with efficient development, scalable manufacturing and sustainable pricing are likely to shape the next era of medicine.

                          Key Concepts: Biotechnology, business, genetics, economics, genomics, entrepreneurship, finance, science, globalization, healthcare, innovation, investing, marketing, artificial intelligence (AI), CRISPR, mRNA

                          Source: Plunkett Research, Ltd., Copyright © 2026

                          What You get

                          Complete data and market research for the industry(s) of your choice, including:

                          • Market Research
                          • Technologies Analysis
                          • Business Intelligence and “hard-to-find” facts
                          • Key Industry Associations (with contact information)
                          • Corporate Executive Contracts
                          • Industry Glossary
                          • Data Export Tools
                          • Top Companies Data